
Fiscal Policy vs Monetary Policy: What’s the Difference?
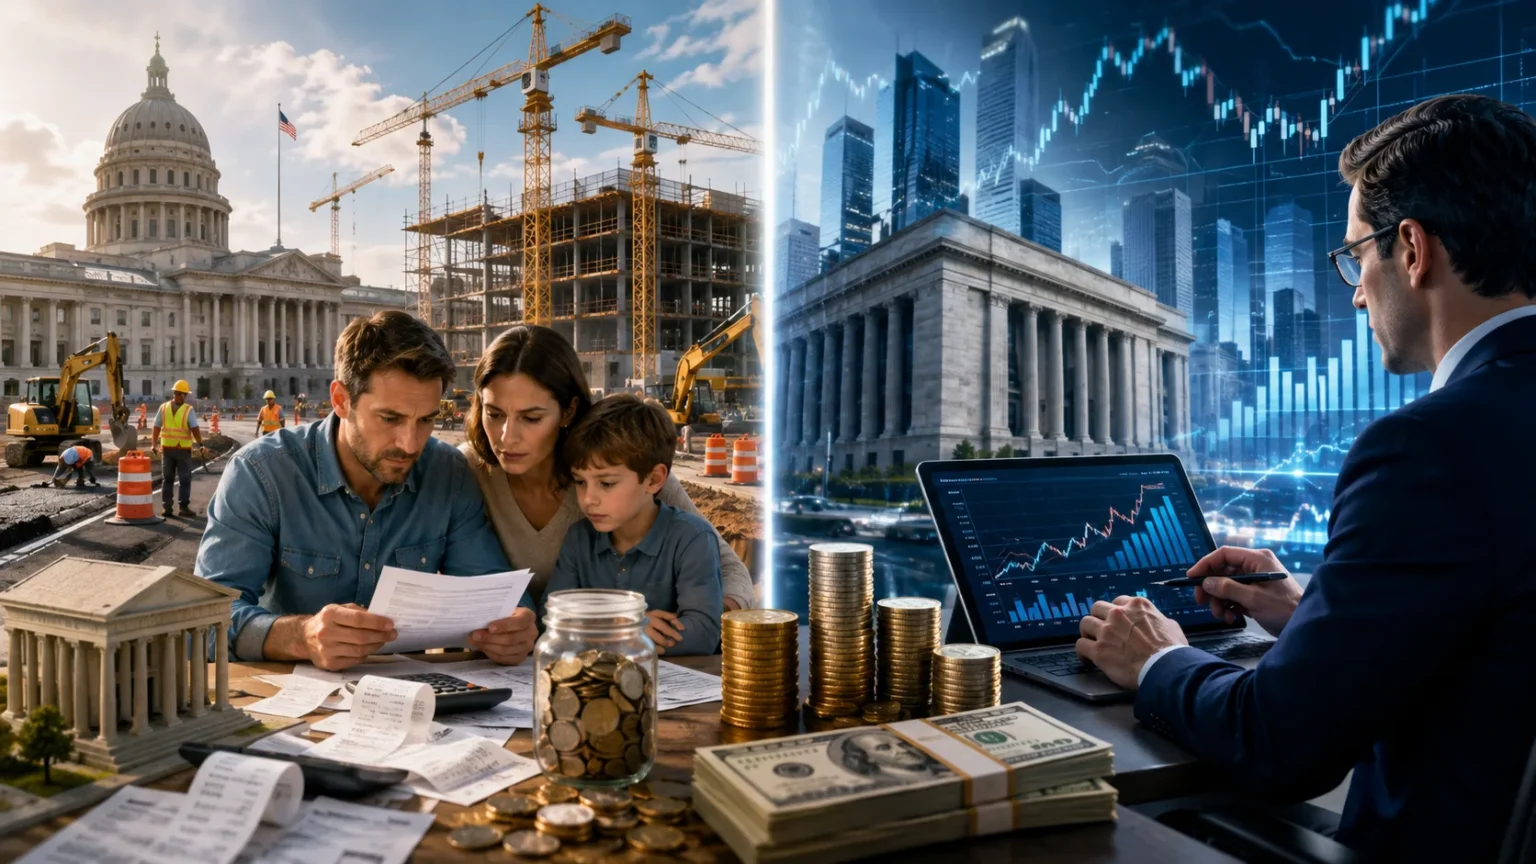
Fiscal policy and monetary policy are two major tools used to influence economic conditions, but they work in different ways and are controlled by different institutions. Fiscal policy involves government decisions about spending, taxation, and borrowing, while monetary policy generally involves central bank decisions about interest rates, money, and financial conditions. Both policies can influence economic growth, inflation, employment, consumer spending, and business investment. Governments and central banks may use them to support an economy during recessions or reduce excessive demand when inflation becomes too high. Understanding fiscal policy vs monetary policy therefore helps beginners make sense of many important economic decisions reported in the news.
Fiscal policy works mainly through the government budget because governments collect taxes and spend money on public services, infrastructure, benefits, defense, education, and other priorities. When a government increases spending or reduces taxes, households and businesses may have more money available to spend. Stronger demand can encourage businesses to increase production and hire workers. Governments can also reduce spending or increase taxes when they want to limit demand or improve public finances. These decisions influence the economy directly because they change the amount of money flowing between the government, households, and businesses.
Monetary policy usually works through the financial system rather than direct government spending. A central bank can raise or lower policy interest rates, which can influence mortgages, business loans, savings rates, credit cards, and other borrowing costs. Lower interest rates tend to encourage borrowing and spending, while higher rates generally make credit more expensive and can reduce demand. Central banks may also use other financial tools when ordinary interest-rate changes are not enough. Monetary policy therefore influences economic behavior by changing financial incentives rather than directly deciding where government money should be spent.
The two policies often pursue similar broad goals even though their methods are different. Policymakers generally want an economy to achieve sustainable growth, stable prices, strong employment, and a stable financial system. Fiscal policy can support these goals through government spending and taxation, while monetary policy can influence borrowing, saving, investment, and inflation through interest rates. The effectiveness of either approach depends heavily on economic conditions. A policy that helps during a recession could create problems if used when the economy is already operating near full capacity.
The easiest way to remember the difference is that fiscal policy comes primarily from government budget decisions, while monetary policy comes primarily from the central bank. Fiscal policy changes government spending and taxes, whereas monetary policy changes financial conditions such as interest rates. Both can affect your job, mortgage, savings, business conditions, and purchasing power. They can also interact with one another, sometimes reinforcing the same economic objective and sometimes pulling in opposite directions. Learning how each tool works provides a foundation for understanding inflation, recessions, unemployment, public debt, and economic growth.
What Is Fiscal Policy and How Does It Work?
Fiscal policy refers to government decisions about spending, taxation, and borrowing that influence economic activity. Governments use fiscal policy to fund essential services while also shaping demand throughout the economy. Spending on roads, healthcare, education, public salaries, infrastructure, and social programs directly adds money to different parts of the economy. Tax decisions influence how much income households and businesses retain for private spending or investment. Fiscal policy can therefore change both the amount of government demand and the financial resources available to the private sector.
Expansionary fiscal policy is generally used when policymakers want to stimulate a weak economy. A government may increase public spending, reduce taxes, or combine both approaches to support household income and business activity. Infrastructure projects can create construction jobs, while tax reductions may leave consumers with more disposable income. Businesses receiving stronger demand may respond by increasing production or hiring additional workers. The objective is usually to prevent a recession from becoming deeper and help economic activity recover more quickly.
Contractionary fiscal policy works in the opposite direction by reducing government spending, increasing taxes, or limiting the growth of public expenditure. Policymakers may use this approach when demand is excessive, inflation is high, or government debt has become a significant concern. Higher taxes can reduce disposable income and consumer spending, while lower government expenditure directly reduces public-sector demand. These changes can help cool an overheated economy. However, contractionary policy can also slow growth and weaken employment if it is introduced too aggressively.
Government borrowing is closely connected to fiscal policy because spending does not always match tax revenue in a particular year. When spending exceeds revenue, the government runs a budget deficit and typically finances the difference by borrowing. During recessions, deficits often increase because tax revenues fall while unemployment benefits and other support payments rise. Borrowing can help governments stabilize economic activity during difficult periods. However, persistently large debt can increase interest costs and reduce the government’s flexibility to respond to future crises.
Fiscal policy also influences the economy through longer-term investments rather than only short-term stimulus. Spending on transportation, digital infrastructure, energy systems, education, healthcare, and research can increase an economy’s productive capacity over many years. Well-designed public investment can reduce business costs and improve worker productivity. Poorly targeted spending, however, may increase debt without generating meaningful economic benefits. The effectiveness of fiscal policy therefore depends not only on how much governments spend but also on when they spend, what they fund, and how efficiently programs are delivered.
What Is Monetary Policy and How Does It Work?
Monetary policy refers to actions taken by a central bank to influence interest rates, credit conditions, inflation, and overall economic activity. Central banks usually have responsibilities related to price stability, and some also have explicit goals involving employment or broader economic performance. Interest rates are the most familiar monetary policy tool because changing borrowing costs can influence household and business decisions. When central banks adjust rates, the effect gradually moves through banks, financial markets, mortgages, savings accounts, and corporate financing. These changes eventually influence spending, investment, employment, and inflation.
Expansionary monetary policy generally involves lowering interest rates or making financial conditions more supportive. Cheaper borrowing can encourage households to purchase homes, vehicles, and other products financed through credit. Businesses may find it more attractive to borrow money for equipment, construction, technology, or expansion. Higher spending and investment can strengthen demand, supporting jobs and economic growth. Central banks usually consider this approach when economic activity is weak and inflation is sufficiently under control.
Contractionary monetary policy involves raising interest rates or otherwise tightening financial conditions to slow excessive demand. Higher rates increase the cost of mortgages, business loans, personal credit, and other borrowing. Households may postpone major purchases, while businesses can cancel investments that no longer appear profitable at higher financing costs. Reduced demand can make it harder for companies to continue raising prices rapidly. This is one of the main ways central banks attempt to bring high inflation back toward a more stable level.
Central banks can also use additional tools when changing short-term interest rates is not enough. During severe financial crises or unusually weak economic periods, they may purchase certain financial assets, provide emergency liquidity, or use other programs to influence longer-term borrowing conditions. These measures are sometimes described as unconventional monetary policy. Their purpose is generally to keep financial markets functioning and support credit when normal policy tools have limited room. Such interventions can be powerful, but they also require careful management because they can influence asset prices and financial risk-taking.
Monetary policy does not affect the economy instantly because borrowers, businesses, and financial contracts take time to adjust. Some homeowners have fixed-rate mortgages that do not change immediately when central banks raise rates. Companies may continue investment projects that were financed before borrowing costs increased. Inflation itself can also respond slowly because wages, rents, and business prices may be set through long-term agreements. Central banks therefore make decisions partly based on expected future conditions rather than only current economic data.
Fiscal Policy vs Monetary Policy: Key Differences
The biggest difference between fiscal policy and monetary policy is who controls each policy. Fiscal policy is determined by governments through budgets, tax laws, public spending programs, and borrowing decisions. Monetary policy is usually managed by an independent or semi-independent central bank according to its legal mandate. This separation matters because governments are directly involved in political choices about taxation and public services. Central banks are generally designed to make monetary decisions with a stronger focus on economic stability and inflation rather than short-term political goals.
The tools used by each policy are also different. Fiscal policy changes government spending, taxes, transfers, and borrowing, while monetary policy changes interest rates and broader financial conditions. A government might stimulate the economy by increasing infrastructure spending or reducing income taxes. A central bank might support the same economy by reducing interest rates so households and businesses can borrow more cheaply. Both can increase demand, but the channels through which they operate are not the same.
Fiscal policy can target specific industries, households, or regions more directly than monetary policy. A government can increase healthcare spending, provide support to low-income families, subsidize energy costs, or invest in a particular transportation project. Monetary policy is generally broader because an interest-rate change affects financial conditions across much of the economy. Higher rates do not selectively target only one city or industry. This makes monetary policy powerful for changing aggregate demand but less precise when policymakers want to support specific groups.
The speed of implementation can also differ. Central banks can often change policy interest rates relatively quickly after scheduled meetings or emergency decisions. Fiscal policy may require legislation, political negotiations, budget approval, and administrative planning before new programs or taxes can take effect. Once fiscal measures begin, however, they can provide direct support to households or projects. Monetary policy may be faster to announce but slower to influence real economic behavior because borrowing decisions adjust gradually.
Another major difference concerns long-term consequences. Fiscal policy can directly increase public debt when governments spend more than they collect in taxes. Monetary policy does not normally finance government spending in the same way, although its actions can influence government borrowing costs and financial markets. Central banks also face risks if rates remain too low or too high for extended periods. Fiscal and monetary policy therefore involve different trade-offs, even when both are being used to influence the same economic problem.
Expansionary Fiscal Policy vs Expansionary Monetary Policy
Expansionary fiscal policy and expansionary monetary policy are both intended to support economic activity, particularly when growth is weak or unemployment is elevated. Expansionary fiscal policy typically involves higher government spending, lower taxes, or increased transfers to households. Expansionary monetary policy generally involves lower interest rates or easier financial conditions. Both approaches attempt to increase aggregate demand, but they reach households and businesses through different channels. Their effectiveness can therefore vary depending on the type of recession and the financial condition of consumers and companies.
Fiscal stimulus can be especially powerful when the government directly spends money on goods, services, or infrastructure. A new transportation project can immediately create demand for construction companies, materials, engineers, and workers once implementation begins. Financial support to households can also protect spending during a downturn. The impact depends partly on whether recipients spend the additional money or save it. Programs directed toward households with immediate financial needs may generate stronger short-term spending effects than benefits given to people who already have significant savings.
Lower interest rates stimulate the economy mainly by making borrowing and investment more attractive. Mortgage payments may become cheaper for new borrowers, businesses may find expansion projects easier to finance, and consumers may be more willing to use credit. Lower rates can also influence financial markets and asset values, potentially increasing confidence and wealth. However, monetary stimulus depends on people being willing and able to borrow. During a deep recession, households may avoid new debt even when rates are very low because they are worried about jobs or future income.
This difference explains why fiscal policy can sometimes become especially important during severe downturns. If interest rates are already extremely low, a central bank may have limited room to reduce them further. Governments can still support demand by spending directly or providing temporary financial assistance. Fiscal policy can also address problems monetary policy cannot solve, such as damaged infrastructure or unusually high healthcare needs. Monetary policy remains useful for keeping credit markets functioning, but direct government action can be necessary when private demand collapses.
Using both policies at the same time can create a stronger recovery when economic conditions genuinely require broad support. Lower interest rates can make business and household borrowing easier while government spending directly supports employment and demand. However, policymakers must eventually adjust as the economy recovers. Maintaining very loose fiscal and monetary policy after demand has already become strong can contribute to inflation. Expansionary policy is therefore most effective when it is matched carefully to the amount of unused capacity and weakness in the economy.
Contractionary Fiscal Policy vs Contractionary Monetary Policy
Contractionary fiscal and monetary policies are generally used when policymakers want to reduce excessive demand, limit inflationary pressure, or improve financial stability. Contractionary fiscal policy can involve higher taxes, lower public spending, or slower growth in government expenditure. Contractionary monetary policy usually involves higher interest rates and tighter credit conditions. Both reduce spending capacity within the economy, but they place pressure on households and businesses in different ways. The choice of policy depends on inflation, government finances, employment, debt levels, and other economic conditions.
Higher taxes reduce the amount of disposable income available to households or the funds businesses can retain for investment. Lower government spending directly reduces demand for goods, services, and labor supplied to the public sector. These measures can slow economic activity, which may help reduce inflation when demand is excessively strong. Fiscal tightening can also reduce budget deficits and slow the growth of government debt. However, cutting spending too rapidly can weaken public services, investment, and employment if the economy is already fragile.
Higher interest rates influence demand through borrowing and saving decisions rather than taxation. Mortgages become more expensive, business financing costs rise, and some consumers postpone credit-financed purchases. Savers may receive higher returns and choose to spend less immediately. When millions of households and businesses make similar adjustments, total demand can decline. This reduced demand can help bring inflation down without requiring the government to change tax rates or specific spending programs.
Monetary tightening often plays the central role in controlling inflation because central banks can adjust rates relatively quickly and apply tighter conditions across much of the economy. Fiscal tightening can complement that effort by reducing government demand instead of forcing monetary policy to do all the work. If a government continues expanding spending aggressively while the central bank raises interest rates, the two policies may partially offset one another. Households then face higher borrowing costs while public spending continues stimulating demand. Coordination can therefore make inflation control more efficient.
Both contractionary approaches involve economic costs when taken too far. Higher interest rates can contribute to falling investment, weaker housing activity, and rising unemployment. Higher taxes or spending reductions can also weaken household income and public-sector demand. Policymakers therefore try to reduce inflation or debt without unnecessarily creating a severe recession. The appropriate balance depends on whether the economy’s main problem is excessive demand, persistent inflation, unsustainable public finances, or a combination of several challenges.
How Fiscal and Monetary Policy Affect Inflation
Inflation can develop when total demand for goods and services grows faster than an economy’s ability to produce them. Fiscal policy can influence this balance because government spending adds directly to demand while taxes affect household and business spending power. If a government increases spending substantially when the economy already has limited spare capacity, inflationary pressure can increase. Conversely, reducing government demand can help cool the economy. The inflation impact depends on timing because the same policy can have very different effects during a recession and during an economic boom.
Monetary policy affects inflation mainly by changing borrowing costs and financial conditions. Higher interest rates reduce some consumer spending and business investment, making demand less intense. Businesses may then have less ability to increase prices because customers become more price-sensitive. Lower rates can stimulate demand, which is useful when inflation is low and economic activity is weak. If monetary conditions remain too loose while supply is constrained, however, stronger demand can eventually contribute to higher inflation.
Neither policy can instantly solve inflation caused primarily by supply shortages. Higher interest rates cannot create more energy, food, computer chips, or housing in the short term. Government spending can sometimes increase supply capacity, but infrastructure and production projects usually require time. Fiscal measures such as temporary subsidies can reduce the price consumers pay for certain products without eliminating the original shortage. Policymakers therefore need to understand whether inflation is being driven mainly by demand, supply, expectations, or multiple factors simultaneously.
Inflation expectations also matter because households and businesses change behavior based on what they believe future prices will do. Persistent fiscal deficits or unusually loose monetary policy can increase concerns about future inflation under some economic conditions. Workers may demand larger wage increases, while businesses may raise prices earlier because they expect costs to rise. Central bank credibility can help keep expectations stable by convincing the public that excessive inflation will be addressed. Fiscal credibility also matters because governments need sustainable long-term plans for spending and debt.
The strongest anti-inflation strategy often requires consistency between fiscal and monetary policy. If a central bank is trying to reduce demand through higher interest rates while government policy strongly increases demand, inflation may take longer to decline. If both policies become extremely restrictive simultaneously, the economy may slow more sharply than necessary. Good economic management therefore involves understanding how the two policies interact. Inflation control is not simply about choosing fiscal policy or monetary policy but about creating an overall policy mix appropriate for current economic conditions.
How Fiscal and Monetary Policy Affect Jobs and Growth
Fiscal policy can influence employment directly because governments purchase services and finance projects that require workers. Infrastructure construction, healthcare funding, education spending, and other programs can create or support jobs. Tax reductions may also increase household spending, giving businesses more reason to hire. During a recession, expansionary fiscal policy can prevent some job losses by supporting demand. However, once the economy is operating near full employment, additional stimulus may create more inflation than sustainable job growth.
Monetary policy influences jobs indirectly through business and household financial decisions. Lower interest rates can encourage companies to invest and expand, potentially increasing demand for workers. Stronger housing activity can support construction employment, while increased consumer spending can help retail, hospitality, and service-sector jobs. Higher rates can slow these processes by making financing more expensive. Employment therefore often weakens after monetary tightening has been in place long enough to reduce overall economic demand.
Economic growth is also affected because GDP includes consumer spending, business investment, government spending, and net exports. Fiscal policy changes government spending directly and can influence consumption through taxes or transfers. Monetary policy influences consumption and investment through credit conditions. Both policies can therefore change short-term GDP growth substantially. Their long-term impact depends more heavily on whether they support productivity, capital investment, education, innovation, and other sources of sustainable economic growth.
There is an important difference between stimulating demand and increasing an economy’s productive capacity. A temporary tax cut may raise consumer spending without permanently increasing the amount the economy can produce. Lower interest rates can encourage investment, but they can also stimulate consumption or asset prices. Fiscal investment in infrastructure, research, or education may increase supply capacity over a longer period when projects are effective. Sustainable growth therefore requires more than simply using policy to make people spend more.
Employment and growth goals can sometimes conflict with inflation objectives. Policymakers may want to support jobs during weak economic conditions, but stimulating demand too strongly can increase inflation. Conversely, reducing inflation through higher rates and lower government demand can slow hiring. Economic policy therefore involves trade-offs rather than perfect solutions. Fiscal and monetary authorities attempt to maintain enough demand for healthy growth while preventing the economy from becoming so overheated that price stability is lost.
Who Controls Fiscal Policy and Monetary Policy?
Fiscal policy is generally controlled by elected governments because decisions about taxation and public spending are political choices. Legislatures or parliaments commonly approve budgets, tax rules, and major spending programs, although the exact process varies between countries. Governments decide how much funding should go toward healthcare, education, defense, infrastructure, social benefits, and other priorities. These choices involve both economic and social objectives. Fiscal policy therefore reflects public preferences, political negotiations, and the financial resources available to the government.
Monetary policy is generally controlled by a country’s central bank rather than elected lawmakers. Many central banks have operational independence so they can make interest-rate decisions without direct short-term political pressure. Their mandates often emphasize maintaining stable prices, and some also include employment or financial stability objectives. Monetary policy committees examine inflation, wages, GDP, unemployment, financial markets, and other indicators before making decisions. Independence is intended to strengthen credibility, although central banks remain accountable under the laws establishing their responsibilities.
The separation between government and central bank responsibilities can reduce the risk that monetary policy is used primarily for short-term political advantage. Politicians may prefer very low interest rates because cheap credit can temporarily support growth before elections. However, keeping rates too low when inflation is rising can damage purchasing power and economic stability. An independent central bank can tighten monetary policy even when doing so is politically unpopular. This institutional structure is designed to prioritize longer-term price stability.
Fiscal authorities and central banks still need to understand one another’s policies even when they operate independently. Government spending decisions affect inflation and economic growth, which central banks monitor when setting interest rates. Monetary policy changes government borrowing costs, which can influence public budgets and debt interest expenses. Their decisions therefore interact even without formal coordination. A large fiscal stimulus can lead to tighter monetary policy if the central bank believes additional demand will increase inflation.
Different responsibilities also mean the public should not assume that one institution controls every economic outcome. Governments cannot directly dictate all private borrowing costs in a market economy, while central banks do not decide how public budgets should be allocated. Both operate within legal, political, and economic constraints. Inflation, unemployment, and growth are also influenced by global trade, technology, demographics, energy prices, and private-sector decisions. Fiscal and monetary policy are powerful tools, but neither institution can completely control the economy.
When Fiscal and Monetary Policies Work Together
Fiscal and monetary policy can reinforce each other during major recessions when economic demand has fallen sharply. Governments may increase spending or provide temporary financial support while central banks lower interest rates and maintain credit availability. Fiscal measures support households and businesses directly, while monetary policy improves financing conditions. Together, these actions can reduce the risk that falling spending leads to deeper job losses and business failures. This combination can be particularly useful when an economy experiences a sudden and severe shock.
Coordination can also matter when inflation is too high. Central banks can raise interest rates to weaken excessive borrowing and spending, while governments avoid adding unnecessary demand through large unfunded spending increases. More restrained fiscal policy can reduce the amount of tightening required from monetary policy. This may lessen the pressure on mortgage borrowers and interest-sensitive industries. When fiscal and monetary policy send consistent signals, households and businesses may also have greater confidence that inflation will eventually return to a more stable level.
Policies can sometimes work against each other, creating unnecessary economic tension. A government might introduce large expansionary spending programs while the central bank is raising interest rates to reduce inflation. Government demand then pushes the economy in one direction while monetary policy attempts to push it in the opposite direction. The central bank may need to keep interest rates higher for longer to compensate. This can increase borrowing costs for households and businesses while making inflation control more difficult.
Complete coordination does not mean central banks should lose their independence or simply follow government instructions. The two institutions have different responsibilities and time horizons, which can provide useful checks and balances. A central bank should still respond to inflation risks even if government policy is expansionary. Governments likewise need to make public spending decisions based on social and economic priorities rather than relying entirely on monetary policy. Effective policy means understanding the interaction between both tools while respecting their separate roles.
The appropriate policy mix changes as economic conditions evolve. Strong fiscal and monetary stimulus may be appropriate during a severe recession but dangerous once demand has recovered and inflation is rising. Tight monetary policy combined with major spending cuts may reduce inflation but could also create an unnecessarily deep downturn if the economy is already weak. Policymakers therefore need timely economic data and flexible strategies. Successful economic management depends on adjusting the mix rather than permanently favoring expansionary or contractionary policy.
Which Is More Effective: Fiscal Policy or Monetary Policy?
There is no universal answer to whether fiscal policy or monetary policy is more effective because each tool works better under different circumstances. Monetary policy is often useful for managing inflation and normal fluctuations in economic demand because central banks can change interest rates relatively quickly. Fiscal policy can be particularly powerful when governments need to support specific households, industries, or public investments. During a severe financial crisis, both may be necessary. The correct choice depends on the cause of the economic problem and the condition of households, businesses, banks, and government finances.
Monetary policy has the advantage of being broad and relatively flexible. Central banks can raise or lower interest rates without passing an entirely new government budget. This allows them to respond to changing inflation and growth conditions more frequently. However, monetary policy can be less effective when rates are already extremely low or when people are unwilling to borrow. It also affects borrowers unevenly, placing significant pressure on households and industries that depend heavily on credit.
Fiscal policy has the advantage of being able to direct support toward particular economic needs. Governments can invest in infrastructure, provide temporary unemployment support, reduce certain taxes, or help regions affected by a major economic shock. Direct spending can stimulate demand even when households are unwilling to borrow. However, fiscal policy may be slow because political approval and project implementation take time. Poorly designed programs can also increase public debt without producing enough economic benefit.
The cause of inflation or recession should therefore guide policy choices. A recession caused by weak household demand may respond well to both lower interest rates and temporary fiscal support. A financial crisis may require central bank liquidity alongside government measures to stabilize banks or protect incomes. Inflation caused by excessive demand may require monetary tightening and fiscal restraint. Supply-side problems may need targeted infrastructure, energy, trade, or productivity policies because neither interest rates nor general stimulus can immediately create missing resources.
The most effective economic strategy is usually not about selecting one policy permanently over the other. Fiscal policy and monetary policy are complementary tools designed to address different parts of economic management. Each has strengths, limitations, side effects, and implementation delays. Using the right tool at the right time can stabilize demand while protecting long-term growth and price stability. Understanding the differences helps people evaluate policy debates without assuming that every economic problem can be solved by taxes, spending, or interest rates alone.
How Fiscal and Monetary Policy Affect Everyday Life
Fiscal policy affects households directly through taxes, public services, benefits, and government programs. A change in income tax can alter how much money workers take home, while changes in sales taxes can affect consumer prices. Government spending determines funding for transportation, healthcare, schools, infrastructure, and many other services people use regularly. Benefit programs can provide financial support during unemployment or economic hardship. Fiscal policy therefore appears in everyday life through both household finances and the quality of public services.
Monetary policy is often felt most strongly through borrowing costs. When central banks raise interest rates, mortgages, business loans, credit cards, and some personal loans can become more expensive. Lower rates can reduce financing costs for new borrowers and encourage home purchases or business investment. Savings rates can also rise when monetary policy becomes tighter, benefiting households with significant cash deposits. These different effects mean higher interest rates can help some people while creating financial pressure for others.
Employment can be influenced by both policies because businesses hire workers when customer demand and investment opportunities are strong. Government spending can directly support jobs, while lower interest rates can encourage private companies to expand. Tight fiscal or monetary policy can reduce hiring when businesses expect weaker sales. These effects often take time and vary considerably between industries. Understanding policy changes can therefore provide useful context for shifts in job opportunities and wage growth.
Inflation also connects both policies to household purchasing power. Fiscal stimulus can support incomes during recessions, but excessive demand may contribute to inflation when supply is already limited. Higher interest rates can reduce inflation over time but may increase mortgage and debt payments before prices stabilize. Households can therefore experience the costs and benefits of economic policy through several channels simultaneously. A policy designed to solve one problem can temporarily create pressure somewhere else.
For individuals, understanding fiscal policy vs monetary policy makes economic news easier to interpret and can improve financial planning. Government budget announcements can signal changes in taxes or public spending, while central bank decisions can affect borrowing and savings rates. Neither policy should cause people to make rushed financial decisions based on one headline. Personal affordability, emergency savings, debt levels, income security, and long-term goals remain more important. Economic knowledge simply provides better context for understanding why financial conditions are changing.
Frequently Asked Questions About Fiscal and Monetary Policy
What is the main difference between fiscal and monetary policy?
Fiscal policy involves government decisions about taxation, spending, and borrowing. Monetary policy is generally controlled by a central bank and uses interest rates and financial conditions to influence inflation and economic activity.
Who controls fiscal policy?
Fiscal policy is generally controlled by elected governments through budgets, tax legislation, and public spending decisions. The exact process depends on the political and legal system of each country.
Who controls monetary policy?
Monetary policy is usually controlled by a country’s central bank or monetary authority. Central banks set or influence interest rates and may use additional tools to maintain price and financial stability.
Which policy is used to fight inflation?
Monetary policy commonly plays the leading role because central banks can raise interest rates to reduce excessive demand. Fiscal restraint can support that effort by limiting government demand and reducing pressure on prices.
Can fiscal and monetary policy be used together?
Yes, both policies can work together during recessions, inflationary periods, or major economic shocks. Their combined effectiveness depends on timing, economic conditions, and whether the two policies are reinforcing or offsetting each other.